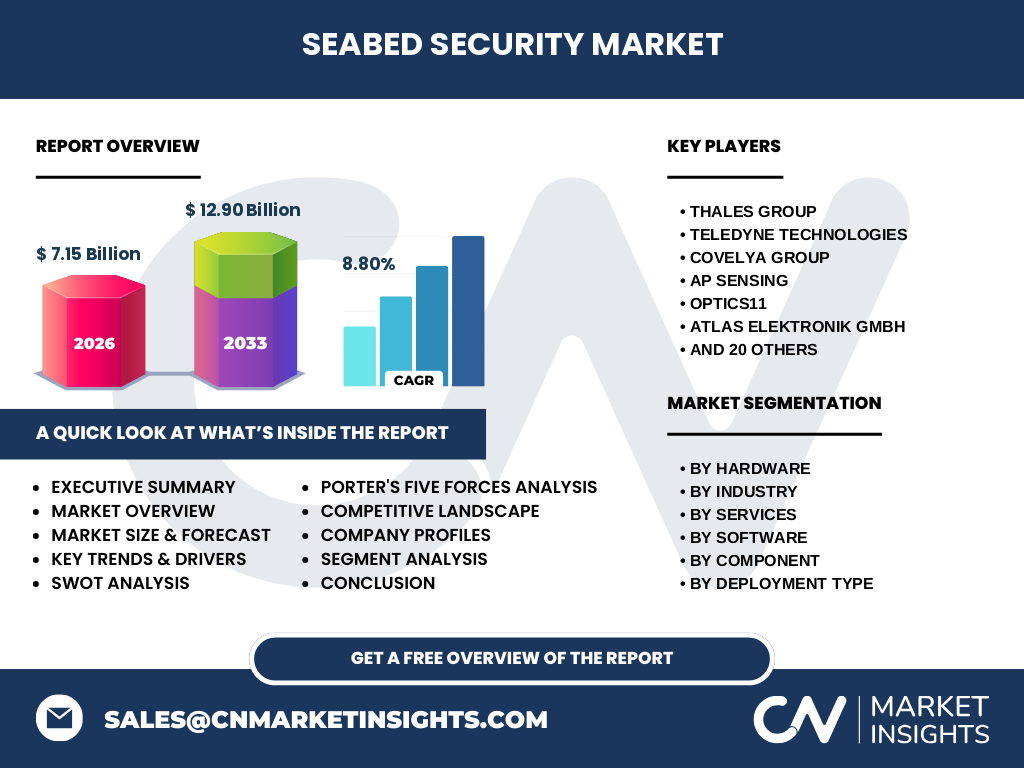
What is the market overview and scope of the Seabed Security Market?
Our research indicates the Seabed Security Market is valued at $7.15 Billion in 2026, encompassing the safeguarding of critical subsea assets against geopolitical sabotage, illegal tapping, and environmental hazards. This domain spans critical infrastructure like submarine communication cables and offshore energy grids.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical tensions threatening submarine data corridors and rising offshore wind installations. Restraints involve exorbitant capital expenditures required for ultra-deep water deployment and complex international maritime jurisdiction hurdles under UNCLOS frameworks.
Emerging trends in the Seabed Security Market
The shift toward autonomous surveillance is reshaping operations. Operators increasingly deploy Autonomous Underwater Vehicles and AI-driven Threat Detection Software to monitor remote undersea assets without risking human divers in hostile environments.
How did COVID-19 impact the Seabed Security Market?
The pandemic caused temporary supply chain bottlenecks for critical titanium alloys and fiber-optic components, delaying offshore deployment schedules. However, our analysis reveals accelerated investments in touchless, remote monitoring software as physical maintenance crews faced severe quarantine restrictions.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high among defense primes and subsea engineering giants. Industry leaders leverage proprietary sonar and ROV technology to secure lucrative government defense contracts, creating formidable entry barriers for niche software startups.
Executive summary of the Seabed Security Market
Our proprietary analysis projects the Seabed Security Market to reach $12.90 Billion by 2033, expanding at a robust 8.80% CAGR from 2027. This growth reflects surging maritime security demands across telecommunications and defense sectors.
Market forecast from 2027 to 2033
Driven by rapid expansion in renewable energy and undersea data pipelines, the market scales upward from its 2026 baseline of $7.15 Billion to hit $12.90 Billion by 2033. This trajectory represents a steady 8.80% CAGR fueled by increased defense spending.
Segmentation analysis by hardware, software, services, and industry
Segmentation spans hardware (Sonar Systems, AUVs, ROVs), software (Threat Detection, Navigation), services (Installation, Consulting), and deployment types. Government And Defense Agencies alongside Telecommunications Companies represent the highest-value end-user segments requiring continuous submarine monitoring.
Geographic distribution and regional performance
Regional performance is dictated by maritime border disputes and offshore energy density. North America and Europe dominate due to heavy military investments and extensive North Sea wind farm arrays, while Asia-Pacific shows the fastest growth driven by critical telecommunications cable hubs.
In-depth regional review of key maritime corridors
European operations focus heavily on protecting cross-border energy pipelines and Baltic Sea communication lines. Meanwhile, the Asia-Pacific theater prioritizes defending contested territorial waters and vital shipping lanes using advanced Autonomous Underwater Vehicles and permanent sensor installations.
Company profiles and strategic positioning of leading firms
Industry titans like Thales Group, Kongsberg Gruppen, and L3Harris Technologies dominate through vertically integrated hardware and software ecosystems. Meanwhile, agile innovators like Anduril and Covelya Group disrupt traditional paradigms with AI-enabled autonomous defense architectures.
Porter's Five Forces analysis of the subsea security sector
Bargaining power of buyers is moderate to high, driven by consolidated defense agencies demanding bespoke capabilities. Threat of new entrants remains low due to extreme capital intensity, severe pressure-testing requirements, and strict military-grade certifications for deep water equipment.
SWOT analysis of the Seabed Security Market
Key strengths lie in advanced acoustic sensors and AUV endurance. Weaknesses involve high maintenance overheads. Opportunities emerge from expanding renewable energy grids, while threats include state-sponsored cyber-attacks targeting subsea data analytics software and navigation systems.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material providers supplying corrosion-resistant titanium and specialized polymers, flows through hardware manufacturers and software developers, and culminates with installation service providers delivering turnkey solutions to Oil And Gas Companies.
Investment insights and high-potential areas
High-potential investment pockets center on Threat Detection Software and Autonomous Underwater Vehicles. Investors should prioritize firms possessing proprietary machine learning algorithms capable of processing high-bandwidth acoustic data in real-time.
Conclusion and key takeaways for stakeholders
The Seabed Security Market represents a vital convergence of national defense and critical infrastructure protection. Achieving an 8.80% CAGR through 2033, success hinges on integrating robust hardware with scalable AI monitoring software.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining maritime trade registry data, primary stakeholder interviews with offshore operators, and secondary macroeconomic defense spending indicators, validated through cross-industry expert consensus panels.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033, analyzing hardware, software, services, and component tiers across shallow, deep, and ultra-deep water operational depths. Limitations exclude inland freshwater bodies and non-commercial recreational maritime security.
Recent developments in subsea defense partnerships
Recent strategic moves feature defense contractors forming joint ventures to integrate sonar systems with advanced surveillance software. Notable partnerships emphasize rapid deployment capabilities for protecting submarine communication cables against emerging geopolitical threats.